According to the Zillow lender marketplace, mortgage rates found room to fall today, taking back some of Thursday’s surge.
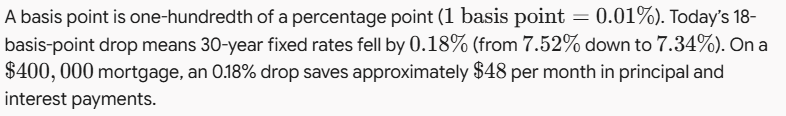
The average 30-year fixed rate today, Friday, October 9, 2026, is 7.34%, down 18 basis points since yesterday. The 15-year fixed loan is currently 6.69%, down 1 basis point from yesterday. The 5/1 ARM is 7.09%, down 4 basis points from Thursday.
Current mortgage rates
Here are the current purchase rates, according to the latest Zillow data, for Friday, October 9, 2026:
- 30-year fixed: 7.34%
- 20-year fixed: 7.22%
- 15-year fixed: 6.69%
- 5/1 ARM: 7.09%
- 7/1 ARM: 6.91%
- 30-year VA: 6.89%
- 15-year VA: 6.65%
- 5/1 VA: 6.36%
Remember, these are national averages and have been rounded to the nearest hundredth.
Current mortgage refinance rates
These are the latest refinance rates, according to the latest Zillow data, for Friday, October 9, 2026:
- 30-year fixed: 7.48%
- 20-year fixed: 7.23%
- 15-year fixed: 6.70%
- 5/1 ARM: 7.30%
- 7/1 ARM: 7.04%
- 30-year VA: 6.86%
- 15-year VA: 6.75%
- 5/1 VA: 6.32%
Again, the numbers provided are national averages rounded to the nearest hundredth. Mortgage refinance rates are often higher than rates when you buy a house, although that’s not always the case.
Free mortgage calculator
Your mortgage rate plays a large role in how much your monthly payment will be. Use this mortgage calculator to see how your mortgage amount, rate, and term length will impact your monthly payments:
Monthly Mortgage Payment Calculator
You can bookmark the tax assistant mortgage payment calculator and keep it handy for future use, as you shop for homes and the best mortgage lenders.
How mortgage interest rates work
A mortgage interest rate is a fee for borrowing money from your lender, expressed as a percentage. You can choose from two types of rates: fixed or adjustable.
A fixed-rate mortgage locks in your rate for the entire life of your loan. For example, if you obtain a 30-year mortgage with a 6% interest rate, your rate will remain at 6% for the entire 30-year term unless you refinance or sell.
An adjustable-rate mortgage locks in your rate for a predetermined period and then adjusts it periodically. Let's say you get a 7/1 ARM with an introductory rate of 6%. Your rate would be 6% for the first seven years, then the rate would increase or decrease once per year for the last 23 years of your term. Whether your rate goes up or down depends on several factors, such as the economy and housing market.
At the beginning of your mortgage term, most of your monthly payment goes toward interest. Your monthly payment toward mortgage principal and interest stays the same throughout the years. However, less and less of your payment goes toward interest, and more goes toward the mortgage principal or the amount you originally borrowed.
Which mortgage term length should you get?
A 30-year fixed-rate mortgage is a good choice if you want a lower mortgage payment and the predictability that comes with having a fixed rate. Just know that your rate will be higher than if you choose a shorter term, and you will pay significantly more in interest over the years.
You may want to consider a 15-year fixed-rate mortgage if you aim to pay off your home loan quickly and save money on interest. These shorter terms come with lower interest rates, and since you're cutting your repayment time in half, you'll save a lot in interest in the long run. But you'll need to be sure you can comfortably afford the higher monthly payments that come with 15-year terms.
Typically, an adjustable-rate mortgage might be suitable if you plan to sell before the introductory rate period ends. Adjustable rates usually start lower than fixed rates, and then your rate will change after a predetermined amount of time. However, 5/1 and 7/1 ARM rates have been similar to (or even higher than) 30-year fixed rates recently. Before getting an ARM just for a lower rate, compare your rate options from term to term and lender to lender.
Are mortgage rates decreasing?
Yes, rates are moving back down after surging yesterday. The average 30-year fixed rate today, Friday, October 9, 2026, is 7.34%, down 18 basis points since yesterday. The 15-year fixed loan is currently 6.69%, down 1 basis point from yesterday. The 5/1 ARM is 7.09%, down 4 basis points from Thursday.
Refinance loans often carry slightly higher rates because lenders view them as higher risk than purchase mortgages. When buying a home, you typically have skin in the game through a down payment and appraisal verification. Refinances—especially cash-out refinances—carry different underwriting guidelines and risk profiles, which leads lenders to charge slightly higher interest rates.
An adjustable-rate mortgage (ARM) offers a fixed interest rate for an initial introductory period (5 years for a 5/1 ARM, 7 years for a 7/1 ARM) before adjusting once per year for the remainder of the 30-year term based on market conditions. ARMs are traditionally useful if you plan to sell or refinance before the initial period ends, but with current 5/1 ARM rates (7.09%) sitting close to 30-year fixed rates (7.34%), the potential long-term risk may outweigh the small rate savings.
Manoj Sharma is a Senior Writer on the banking team at Tax Assistant. He provides information on budgeting, bank accounts, the banking industry, and other related topics. Using original data and methodologies, he helps you identify the best financial institutions, accounts, and products tailored to your needs. Manoj holds a degree in Journalism and Political Science from Syracuse University. All articles are strictly reviewed and fact-checked by our panel of expert Chartered Accountants, including CA Devendra Saini, CA Nikhil Khunteta, and CA Ankit Goyal