Mortgage discount points are an optional fee that some borrowers choose to pay to their lender in exchange for a lower interest rate for their mortgage loan.
As a general rule, paying points might be a smart idea if you plan to keep your mortgage for many years. If you plan to sell or refinance within a short timeframe, paying points may not make sense.
What are discount points on a mortgage?
The term “points” refers to an upfront fee that’s based on a percentage of the loan amount. One point equals 1% of the loan amount, so for a $400,000 mortgage, one point would cost $4,000. Some lenders allow fractional points, such as one-eighth, one-quarter, or one-half of one point.
However, the rate reduction is not one-to-one. One discount point typically lowers your interest rate by 0.25%. That means paying $4,000 for one discount point on a 7% mortgage would lower the rate to 6.75%.
Not every discount point program is the same. A lender’s cost-to-reduction ratio can vary based on the market and their own pricing strategy. So try to compare several lenders before you commit.
How to decide
It’s not always easy to determine whether paying discount points makes sense. These three tips may help you decide.
Tip 1: Prepare a breakeven analysis
A breakeven analysis compares the cost of your discount points to your monthly savings from your lower rate. This analysis can help you figure out when your total savings will equal your upfront cost.
To calculate your breakeven, divide the total cost of your discount points by your monthly savings. The resulting number is how many months it’ll take you to recoup the costs.
As a general rule, paying points may be more attractive if you’re planning to keep your home and your mortgage for at least a few years after you recoup your upfront cost.
For example, one discount point on a fixed 30-year $400,000 mortgage at a 7% interest rate lowers your rate to 6.75% and costs $4,000. This saves about $67 per month, which means you’re breaking even in roughly 60 months or about five years.
That pattern holds no matter how many points you buy. Here’s the same $400,000 loan at different point amounts:
| Points | Cost | Rate | Monthly payment | Monthly savings | Break-even |
|---|---|---|---|---|---|
| 0.5 | $2,000 | 6.88% | $2,628 | $33 | 60 months |
| 1 | $4,000 | 6.75% | $2,594 | $67 | 60 months |
| 2 | $8,000 | 6.5% | $2,528 | $133 | 60 months |
| 3 | $12,000 | 6.25% | $2,463 | $198 | 61 months |
Assumes a 30-year fixed loan at a 7% base rate and 0.25% off per point. Actual pricing varies by lender.
Notice that the break-even barely moves — roughly five years whether you buy half a point or three. Doubling the points doubles both your cost and your monthly savings, so they cancel out. The number of points you buy isn’t really the decision. How long you’ll keep the mortgage is.
Stay with the loan longer, and the savings keep compounding. Over a full 30-year term, that one point cuts your total interest from about $558,000 to roughly $534,000 — $24,054 saved on a $4,000 cost, or about $20,000 net.
That figure is the best case, not the expected case. Most borrowers sell or refinance long before year 30, which is why your break-even date matters more than the lifetime number. Selling the home or refinancing before you break even means you’ve paid for discount points but didn’t realize all the savings.
Selling the home or refinancing before you break even means you’ve paid for discount points, but you didn’t realize all the savings.
Tip 2: Consider your cash position
You can pay for discount points upfront in cash, along with your closing costs. But if your cash is limited or you’re planning to make a lot of repairs or improvements to your home right away, you may not want to pay discount points upfront.
Two other options are to finance discount points as part of your loan amount, which may increase your payment or interest expense, or negotiate for the seller of the home you want to buy to pay discount points for you.
Tip 3: Consider your income tax situation
Mortgage discount points may be tax-deductible. The IRS treats points like prepaid mortgage interest, so claiming them can lower your taxable income for the tax year in which you paid them. However, you must meet IRS requirements.
To start, you’ll have to itemize your tax return to claim the deduction. The points must be for a loan used to buy or significantly improve your primary residence. Discount points on refinanced mortgages are handled differently. On a refi, points must generally be deducted ratably over the life of the loan rather than in the year paid.
There are several additional IRS rules, and they can be complex. It’s worth discussing your specific situation with a tax professional.
Lender credits: the opposite of discount points
Discount points let you pay cash upfront to lower your rate. Lender credits run the same trade in reverse: you accept a higher interest rate, and in exchange the lender gives you money toward your closing costs. You’ll sometimes hear them called negative points or rebate pricing.
The pricing works out roughly symmetrically. Where one discount point might cost 1% of your loan to cut your rate by 0.25%, accepting a rate 0.25% higher might earn you a credit worth about 1% of your loan.
Using the same $400,000 mortgage from earlier: instead of paying $4,000 to drop your rate from 7% to 6.75%, you could take 7.25% and receive roughly $4,000 toward closing costs. Your monthly payment rises from $2,661 to $2,729 — about $68 more per month.
That’s the trade. You keep $4,000 in your pocket at closing and pay for it over time. After about 59 months, or just under five years, the extra interest catches up to the credit you received. Stay in the loan longer than that and the credit has cost you money; move or refinance sooner and you come out ahead.
You may notice that’s nearly the same break-even as buying a point. It’s the same calculation, just pointed the other direction — which is why the real question with both is always how long you plan to keep the mortgage.
Two rules worth knowing:
- Lender credits can only be applied to closing costs. You can’t put them toward your down payment, and you can’t take the leftover as cash.
- If the credit exceeds your actual closing costs, you generally lose the difference — so there’s no benefit to taking a bigger credit than you need.
When a lender credit makes sense: You’re short on cash at closing, you expect to move or refinance within a few years, or you’d rather keep your savings for repairs, furnishing, or an emergency fund than sink it into a lower rate.
When it doesn’t: You’re planning to stay put long-term. Over 30 years, that 0.25% costs about $24,300 in extra interest — roughly six times the credit you received.
Seller-paid discount points
Sometimes sellers are willing to buy mortgage points on the buyer’s behalf. It’s one of many seller concessions buyers can ask for, especially in cooling housing markets where there are more homes than there is demand.
With the seller buying down the interest rate, you get the full benefit of a rate reduction without much of the downside.
And in a high-interest-rate environment, the monthly savings from a seller rate buydown could be more substantial than asking for a lower purchase price.
Discount points or temporary buydown?
Discount points are a permanent rate buydown. However, there’s also a temporary buydown option.
With a temporary buydown, you or the seller pays the upfront cost for a short-term rate reduction, usually lasting one to three years. It’s often a strategy buyers choose if they plan to sell or refinance before the temporary buydown period ends.
Temporary buydowns typically have the lowest rate in the first year, with increases each year thereafter, depending on the structure.
For example, a 2-1 buydown lowers your rate by 2 percentage points in the first year and 1 percentage point in the second year. From year three on, you pay your full rate for the rest of the loan. (That’s what the name means — 2 points off, then 1 point off.)
On a $400,000 loan with a 7% note rate, you’d pay 5% in year one, 6% in year two, and 7% from year three forward — monthly payments of about $2,147, then $2,398, then $2,661.
“Should I pay discount points?” is a complicated question since you have to consider your upfront spending, future costs, breakeven points, and more. Do your best to think about your plans for the future and run the numbers to make sure you feel comfortable with your monthly payment before you decide to pay points—or not.
Buy Down” Break Even Point Calculator
You don’t need a special “points calculator” to determine the amount of mortgage points being charged. There are three steps to determine if is it worth paying points:
- Calculate the amount of mortgage points being charged
- Determine the monthly savings from the lower interest rate
- Figure out the break even point – i.e. how long before the savings justify the costs
Calculate Points Charged
One mortgage point on a $200,000 loan amount results in a $2,000 discount point since a point is 1% of the loan amount. For another example, on the same $200,000 loan amount a half a point (.5%) would be $1,000.
Mortgage points can be any amount but typically range from 0%to 2%. Let’s assume $2,000 in discount points are being charged for our example.
Determine Monthly Savings with Lower Rate
Now let’s assume the $200,000 loan amount has an interest rate of X% and that paying one point of $2,000 (1% of the loan amount) will lower the interest rate by .25%. This will result in about a $30 per month savings.
Break Even Point
Taking the points paid ($2,000) and dividing it by the monthly savings ($30) results in a 66.6 month break even, or 5.5 years (66 months / 12). This means the monthly savings will justify the costs if someone plans on keeping the mortgage for longer than 5.5 years.
Let’s do another quick example but have the costs be two points (2%) to save the .25% in rate. The break even point calculation would be $4,000 / $30 = 133 months = 11 years.
In this instance it really doesn’t make sense to pay $4,000 today and have to wait over a decade to see the benefit of saving only $30 per month.
Are Mortgage Points Tax Deductible?
First and foremost, consult your CPA for accurate tax advise.
Mortgage points are tax deductible so long as they are true discount points to buy down the interest rate. Because mortgage interest is tax deductible the mortgage points paid to lower the interest rate are like prepaying interest.
Tax deductible points will typically appear as Discount Points – not Origination Points. The transaction type impacts the timing of when the tax deduction can be realized.
Tax Deduction for Purchases
Mortgage points paid at a purchase closing are deductible for that tax year. Mortgage points not paid directly by the buyer have to be prorated over the life of the loan.
For example, if $1,000 in points were charged but the borrower only brought $750 to closing and the remaining $250 was paid via seller concessions or premium pricing, then only $750 is allowed to be deducted and the remaining $250 has to be spread out over the life of the loan.
Note: if the points paid were in excess for what is “common and customary” then the points need to be deducted over the life of the loan. Consult your CPA for what’s considered “common and customary.”
Tax Deduction for Refinances
- Points paid in association of a refinance have to be allocated over the life of the loan. This includes Home Equity Lines of Credit (HELOC).
Tax Deduction for Second Homes
- Any points paid for loan pertaining to a second home must be deducted over the life of the loan, regardless if it’s a purchase or a refinance.
Tax Deduction for Home Improvement Loans
- All points paid in association with home improvement loans are tax deductible in the tax year that the points were paid.
Mortgage Ending Early
The timing on tax deductions for mortgage points changes when a mortgage ended early due to prepayment, refinance, or sale of the home.
Any “unused” portion of points that are being deducted for the life of the loan can be “accelerated” and deducted in full. The exception to this rule is that if the loan is refinanced with the same servicer. As a result the points still have to be allocated over the life of the loan.
Discount points are an upfront fee paid to your lender at closing in exchange for a lower interest rate over the life of your loan. One point costs 1% of your total loan amount (e.g., $4,000 on a $400,000 mortgage). Typically, each point reduces your interest rate by 0.25%, which lowers your required monthly mortgage payment.
Divide the total upfront cost of the discount points by your monthly savings. The resulting number gives you the number of months required to recoup your initial cost:
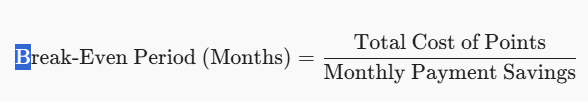
If you keep your mortgage longer than the break-even period (typically around 5 years), paying for points will save you money overall.
They are exact opposites:
Discount points: You pay cash upfront at closing to secure a lower interest rate.
Lender credits: You accept a higher interest rate in exchange for cash from the lender applied toward your closing costs.
If you plan to stay in the home long-term, discount points save money over time. If you are short on cash at closing or plan to move/refinance within a few years, lender credits can lower your initial out-of-pocket expenses.
Yes, but conditions apply depending on the loan type:
Primary Residence Purchase: Points are generally fully deductible in the tax year you pay them, provided you itemize your deductions and meet IRS criteria.
Refinance or Second Home: Points cannot be deducted all at once; they must be deducted ratably (spread out evenly) over the full term of the loan.
Seller-Paid Points: Any portion paid through seller concessions cannot be deducted immediately in full and must be spread across the loan term.
Discount Points (Permanent Buydown): Reduce your interest rate for the entire 30-year term of the mortgage.
Temporary Buydown (e.g., 2-1 Buydown): Lowers your interest rate temporarily for the first 1 to 3 years of the loan (e.g., 2% lower in Year 1, 1% lower in Year 2, and the full rate starting in Year 3). This is typically funded upfront into an escrow account by the home seller or buyer.
Manoj Sharma is a Senior Writer on the banking team at Tax Assistant. He provides information on budgeting, bank accounts, the banking industry, and other related topics. Using original data and methodologies, he helps you identify the best financial institutions, accounts, and products tailored to your needs. Manoj holds a degree in Journalism and Political Science from Syracuse University. All articles are strictly reviewed and fact-checked by our panel of expert Chartered Accountants, including CA Devendra Saini, CA Nikhil Khunteta, and CA Ankit Goyal