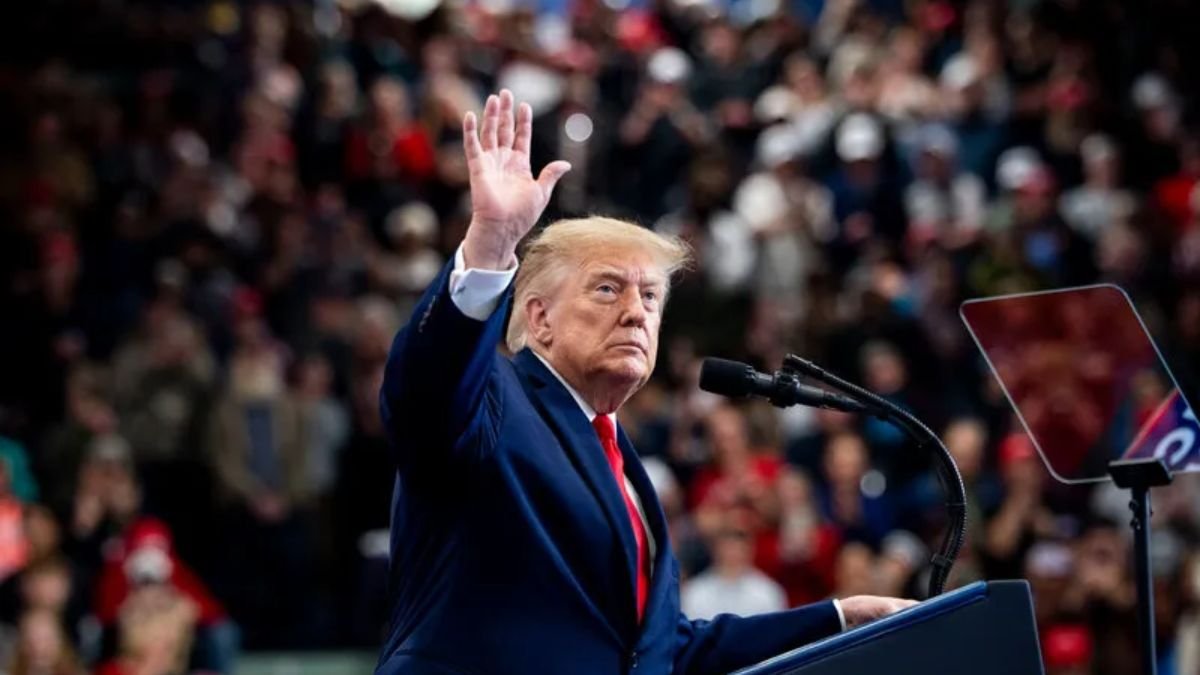
When inflation hits your wallet, it’s natural to look for someone to blame — and often, the president takes the heat. But how much control does the president really have over inflation? Here’s what you need to know about what causes inflation and who’s responsible for managing it.
What is inflation?
Inflation refers to the increase in prices for goods and services over time. When prices rise, your purchasing power decreases, and your money doesn’t go as far as it used to, making it more difficult to cover everyday expenses, save money, and build wealth.
There are key economic indicators that economists use to track inflation. One of the most common is the Consumer Price Index (CPI).
The CPI measures the average change over time in the prices paid by urban consumers for a fixed basket of goods and services, including food, fuel, housing, energy, clothing, and healthcare.
According to the latest CPI data, inflation heated up to 3.7% annually in September as energy prices jumped, increasing from 3.4% in August. On a monthly basis, prices rose by 0.6% in September, up from 0.4% a month earlier.
What causes inflation?
There are several factors that can cause inflation, including changes to supply and demand, monetary policy, and supply chain disruptions.
For example, inflation can increase when there is widespread demand for goods and services, and that demand outpaces the available supply. When companies can’t keep up with the demand, prices skyrocket, driving inflation.
An increase in the money supply can also cause the inflation rate to fluctuate.
“When more money exists, more money tends to be spent, which creates shortages of products and drives up prices,” said Mark Pingle, a professor of economics at the University of Nevada.
Does the president control inflation?
The president can influence inflation indirectly through fiscal policy. For instance, tax cuts or stimulus spending can increase consumer demand and raise the money circulating in the economy, which may contribute to inflation. Tariffs can also push prices higher by raising import costs.
However, the primary responsibility for controlling inflation lies with the Federal Reserve, the country’s central bank. More specifically, the Federal Open Market Committee (FOMC) is a committee within the Fed responsible for maintaining maximum employment and stable prices in the U.S. It does this by raising or lowering the federal funds rate and buying or selling securities to control the money supply in support of that goal.
The president has some influence here as well, as they are responsible for nominating the seven members of the Board of Governors who serve on the FOMC and oversee the 12 Reserve Banks.
However, it’s important to note that the Fed operates independently of the White House; monetary policy decisions are made based on long-term economic objectives, not short-term political pressure.
Money moves to make when inflation is high
Rising inflation can negatively impact your personal finances. Pingle explained that inflation is a lot like an income tax because it reduces your buying power. “When the government acts in ways that generate inflation, it does not take your money, but it has the same effect because you are less able to buy,” he said.
For example, say you head to the grocery store for eggs, milk, and bread. The total cost of your groceries is $10. However, when you return to the store next month to buy the same items, the total cost is now $12 due to inflation. That $10 doesn’t go as far as it used to, and you need more of your income to cover the same essentials.
When inflation is high, it’s important to take steps to mitigate the negative impact on your budget:
- Cut out non-essential spending: When prices are higher than normal, looking for ways to free up some cash flow is a good first step. Review your budget and recent bank statements to get a better sense of where each dollar is going. Then, see if there are areas where you can afford to cut back. That way, when essential expenses increase in price, you have the extra money in your budget to cover it.
- Look for ways to boost your income: When your monthly expenses increase, you may need to find ways to earn more so your income keeps pace. You might consider making the case at work for a raise or promotion, picking up a side gig, or turning your clutter into cash by selling items you don’t use anymore.
- Rethink your savings strategy: Paying more for your regular expenses could mean having to scale back on how much you set aside for savings. However, with the right type of bank account, you can ensure the money you do have saved works harder for you. Check out our lists of the best high-yield savings accounts and CDs that can help your balance grow with today’s top interest rates.
Frequently Asked Questions (FAQs)
No, the president does not have direct control over inflation. Primary responsibility lies with the independent Federal Reserve, which manages monetary policy. However, the president can indirectly influence inflation through fiscal policies such as stimulus spending, tax cuts, tariffs, and executive decisions.
Economists primarily track inflation using the Consumer Price Index (CPI). The CPI measures the average change over time in the prices paid by urban consumers for a standard basket of goods and services, including housing, food, energy, healthcare, and transportation.
The Federal Open Market Committee (FOMC) within the Federal Reserve adjusts the federal funds rate and buys or sells government securities to manage the money supply. Raising interest rates slows down borrowing and spending to cool off rising prices.
When more money enters circulation without a corresponding increase in available goods and services, consumer demand spikes. When supply cannot match this demand, shortages occur, driving prices higher and reducing overall purchasing power.
You can mitigate the impact of inflation by auditing your budget to cut non-essential spending, finding ways to boost your income (such as negotiating a raise or starting a side gig), and moving cash savings into high-yield savings accounts (HYSAs) or CDs to maximize interest returns.
Suresh holds a Master of Commerce (M.Com) degree and is a dedicated personal finance researcher and writer. Combining his advanced academic background in commerce with deep industry research, he covers complex topics like taxation, banking systems, credit analysis, and personal finance strategies. As the founder of Tax Assistant (taxassistant.org), Suresh is committed to translating complicated financial guidelines and economic data into simple, accurate, and actionable educational resources for everyday readers.
