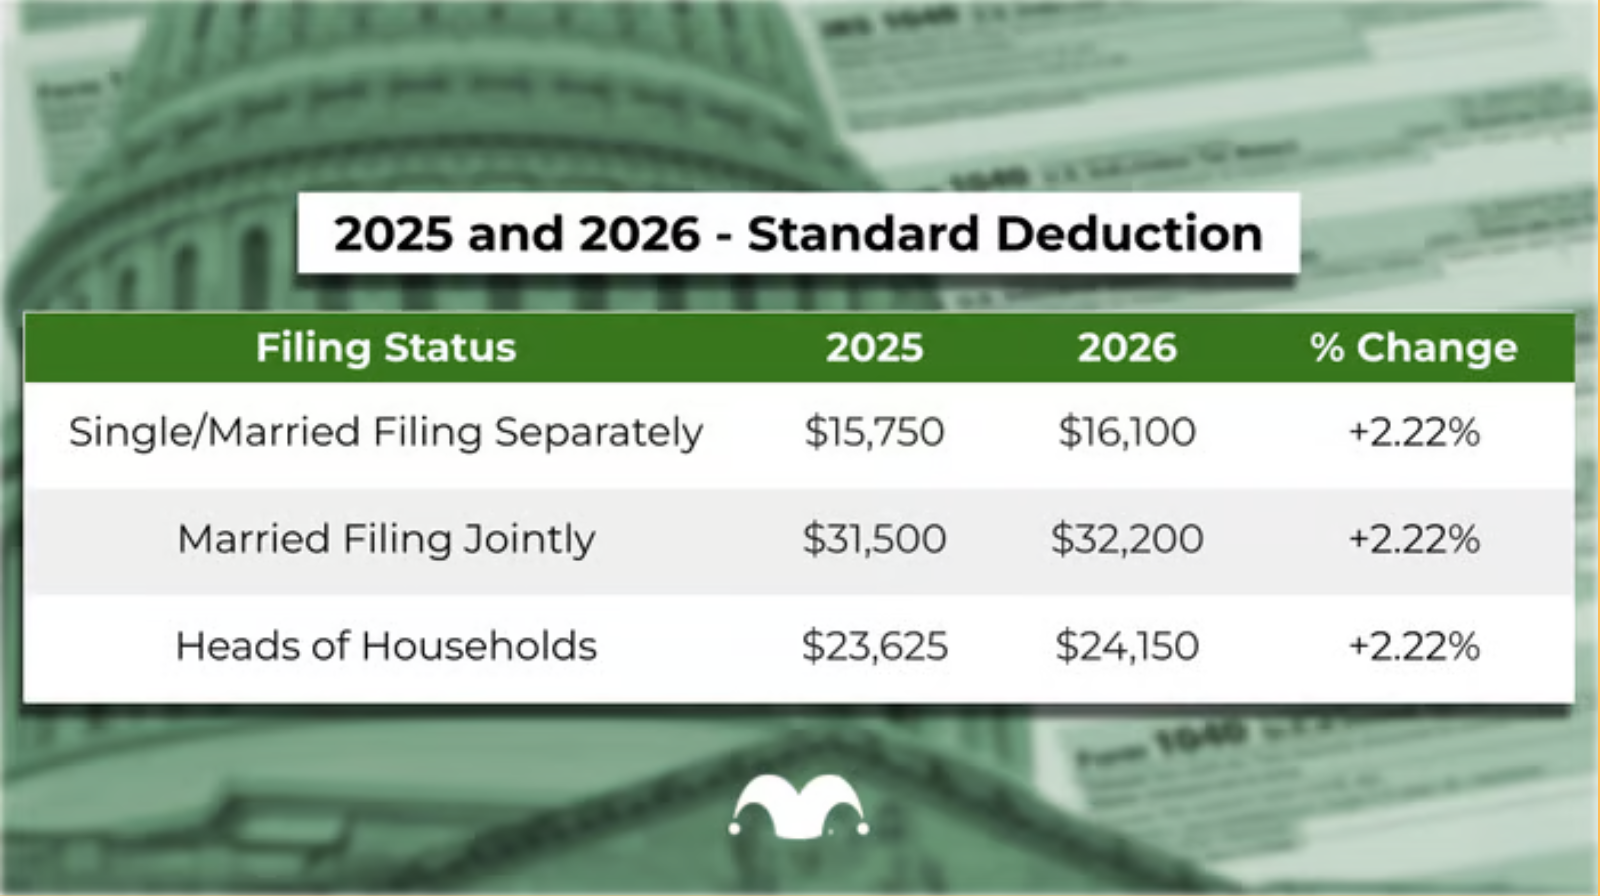
The IRS has officially released the standard deduction adjustments for the 2026 tax year (for taxes filed in early 2027). These updated baseline figures reflect a 2.2% cost-of-living bump from 2025.
2026 Base Standard Deduction
| Filing Status | 2026 Standard Deduction | Change from 2025 |
| Single | $16,100 | +$350 |
| Married Filing Jointly | $32,200 | +$700 |
| Head of Household | $24,150 | +$525 |
| Married Filing Separately | $16,100 | +$350 |
| Qualifying Surviving Spouse | $32,200 | +$700 |
Extra Deductions for Seniors & Blind Taxpayers
If you are legally blind or aged 65 and older by December 31, 2026, you can stack additional amounts on top of your base deduction.
- Single or Head of Household: +$2,050 per qualification (up to $4,100 if both apply).
- Married or Surviving Spouse: +$1,650 per qualification, per person (up to $3,300 per individual if both apply).
The New Senior Bonus Deduction: Under the One Big Beautiful Bill Act (OBBBA), taxpayers aged 65 and older can claim an additional $6,000 senior deduction on top of the standard amounts. This benefit fully applies if your modified adjusted gross income (MAGI) is under $75,000 ($150,000 for joint filers) and gradually phases out above those tiers.
Rules for Dependents
If you can be claimed as a dependent on someone else’s 2026 tax return, your standard deduction is capped at whichever of the following two amounts is greater:
- $1,350
- Your earned income plus $450 (up to the standard baseline limit for your filing status, which is $16,100).
Suresh holds a Master of Commerce (M.Com) degree and is a dedicated personal finance researcher and writer. Combining his advanced academic background in commerce with deep industry research, he covers complex topics like taxation, banking systems, credit analysis, and personal finance strategies. As the founder of Tax Assistant (taxassistant.org), Suresh is committed to translating complicated financial guidelines and economic data into simple, accurate, and actionable educational resources for everyday readers.