When you deposit money into a CD, you essentially make a promise to the bank that you’ll keep that money invested for the agreed-upon term. Breaking that promise by withdrawing your money early can impact the bank or credit union’s bottom line. So, they’ll recoup their costs by charging you an early withdrawal penalty.
Incurring an early withdrawal penalty means forfeiting some — or all — of the interest you’ve accrued. And in some cases, you could also lose part of your initial deposit. But if you’re able to earn a higher return by investing your money elsewhere, it may be worth breaking your CD and paying the fee.
How do CD early withdrawal penalties work?
CDs are time-deposit accounts that require you to leave your money in the account for a specified period (such as 6 months or one year) in exchange for a fixed interest rate. If you break that agreement, you must pay a fee known as an early withdrawal penalty.
The specific penalty you’ll pay depends on the CD’s term, how much you have in the account, and the individual bank’s policies. Note that while there is a minimum penalty set by federal law, there is no maximum. However, many financial institutions have similar policies.
The penalty is usually calculated as a portion of the interest earned — or the interest that would have been earned — over a specified period. CDs with longer terms usually require you to forfeit more interest.
In some cases, there could be additional penalties. For example, if there was a sign-up bonus for opening the CD, you might lose the bonus too.
CD early withdrawal penalty examples
| CD TERM (MONTHS) | INTEREST PENALTY (DAYS) |
|---|---|
| Up to 12 | 60 |
| 13-36 | 90 |
| 37 or more | 180 |
Is it ever worth paying an early withdrawal penalty?
Ideally, if you put money in a CD, you should leave it there until it reaches maturity. Once the term is up, you receive your principal deposit, plus all the interest you earned.
That said, there may be situations in which you could actually come out ahead by breaking your CD early. Namely, if you can save more money than you lose — or earn more money by moving the cash elsewhere — it’s worth making an early CD withdrawal. Here are some circumstances where you might end up benefiting:
You need to cover a financial emergency
If you’re facing an unexpected expense, such as a major medical bill, car repair, or job loss, withdrawing money from a CD may be a better option than taking on expensive debt. In most cases, you’d end up paying much more in interest charges than you’d lose to an early withdrawal penalty.
You can earn significantly higher interest elsewhere
If interest rates have gone up considerably since you opened your CD, you may be able to earn more by withdrawing your money early and reinvesting it in a new CD with a higher APY.
For example: Say you have $20,000 in a CD earning 2.5% APY, with two years remaining until maturity. Your bank charges an early withdrawal penalty equal to six months of simple interest, or about $250.
If you withdraw your money, pay the penalty, and reinvest the remaining $19,750 in a new two-year CD earning 4.5% APY, you’d earn approximately $1,818 in interest over two years. By comparison, leaving the original $20,000 in your existing CD would result in just $1,013 in interest earnings over the same period.
In this case, even after accounting for the penalty, you’d come out roughly $555 ahead by switching CDs.
You want to pay off high-interest debt
If you’re carrying credit card debt or of high-interest loan, using money from a CD to pay down your balance could save you substantially more in interest than you’d lose through an early withdrawal penalty.
For example, say you have $5,000 in credit card debt with a 24% APR. You also have $5,000 in a CD earning 3% APY.
Your credit card debt would cost you about $1,200 in interest charges over a year (assuming the balance stayed the same). Meanwhile, your CD would only earn about $150 over that same period. So, after one year, you’d still be down a total of $1,050.
However, using the money in your CD to eliminate your debt means you’d save $1,200 in interest charges for the year. Plus, you’d be debt-free going forward, allowing you to set aside more income toward savings or other financial goals.
How to calculate an early withdrawal penalty
To calculate your early CD withdrawal penalty, start by looking up your account agreement. That’s where you’ll see the details of how your penalty is calculated. In most cases, the formula will look like this:
(Interest rate / 365) × penalty days × original deposit = penalty
Let’s say you deposited $5,000 to a CD with 4% APY, and the penalty is 60 days’ worth of interest. Here’s how you would calculate your early withdrawal penalty:
(0.04 / 365) × 60 × $5,000 = $32.88 penalty
By comparison, here’s what you would pay for an early withdrawal on a $20,000 CD with 4% APY and a 180-day interest penalty:
(0.04 / 365) × 180 × $20,000 = $394.52 penalty
How to avoid early withdrawal penalties
In most cases, the only way to avoid early withdrawal fees is through preventative steps you take before opening a CD. However, in rare cases, you might be able to avoid fees after opening an account. Here are your options.
Tap your savings
For emergencies, the best alternative to an early CD withdrawal is to use money from your savings.
Unfortunately, not everyone has an emergency savings fund. But moving forward, you can reduce the temptation to make an early CD withdrawal by building an emergency savings fund — and depositing it to a savings account where there’s no withdrawal penalty — before setting up a CD.
Request a waiver
If you’re facing difficult circumstances, your bank or credit union might be willing to waive the early withdrawal penalty. For example, if you’re impacted by a major financial crisis or the owner of the CD becomes disabled or passes away, you may be able to request a fee waiver.
No-penalty CD
Another option is to choose a CD that allows early withdrawals (no-penalty CD), or choose a CD that allows you to make penalty-free withdrawals at set intervals.
The upside of going this route is you have easier access to your money. The downside? You won’t earn as much interest since these types of CDs typically pay lower rates.
CD laddering
A CD ladder is an investment strategy where you set up multiple CDs with staggered maturity dates. The main benefit is that you can still earn interest on your deposits, but you’ll have more frequent access to your money as the different accounts mature in case you want to use it or move it elsewhere.
CD loan
There’s a chance your bank or credit union offers another option: a CD-secured loan or CD loan. With these loans, you can often borrow up to the full balance of the CD and pay it back by the CD maturity date.
With CD loans, you use the funds in your CD as collateral, meaning the money helps you qualify for the loan, and the rates might be lower than a loan with no collateral (like a personal loan). However, you can also lose your CD deposit if you miss your payments. On top of that, you’ll lose money to interest charges, since banks often set their CD loan rates roughly 2% higher than what a CD earns.
frequently asked questions (FAQs)
Most banks calculate the penalty as a specific number of days or months of simple interest earned on the amount withdrawn. The exact formula is: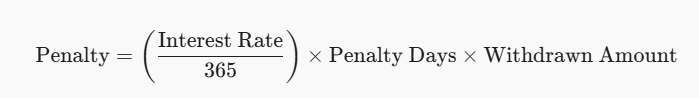
CDs with longer terms (e.g., 3 to 5 years) generally carry larger penalties (such as 180 days of interest or more) compared to short-term CDs (e.g., 60 to 90 days of interest for terms of 12 months or less).
Yes. If you withdraw your money early in the CD term before you have accrued enough interest to cover the calculated fee, the bank will deduct the remaining penalty balance directly from your original principal deposit.
Yes, in three main situations:
Higher Interest Rates: If market interest rates have risen significantly, moving your money into a new CD with a much higher APY can earn you more net interest over time, even after paying the penalty.
High-Interest Debt: Using CD funds to pay off high-interest debt (such as a 24% APR credit card) will save you far more in interest charges than you forfeit in CD penalties.
Avoiding Expensive Credit: Using your CD to cover an unexpected emergency is often far cheaper than taking on high-interest personal loans or credit card debt.
You can avoid early withdrawal penalties by taking preventative steps when choosing your financial accounts:
Build an emergency fund: Keep liquid cash in a high-yield savings account so you don’t need to touch locked CD funds.
Choose a No-Penalty CD: These CDs allow penalty-free withdrawals after an initial holding period (usually 6–7 days), though they typically offer slightly lower interest rates than traditional CDs.
Build a CD ladder: Split your money across multiple CDs maturing at staggered intervals (e.g., 1, 2, and 3 years) so you have periodic, penalty-free access to cash.
While rare, financial institutions may waive the early withdrawal penalty under specific hardship circumstances, such as the death or legal incompetence of the account owner, or during certain federally declared natural disasters and severe financial crises. You must contact your bank directly to request a hardship waiver.
Suresh Saini is the Founder and Lead Financial Researcher at Tax Assistant. He holds a Master of Commerce (M.Com) degree with a specialized focus on Advanced Accountancy, providing him with a robust academic and analytical foundation in complex accounting principles, credit systems, and personal finance structures.
Driven by a passion to democratize financial literacy, Suresh has spent years analyzing and decoding shifting fiscal guidelines. At Tax Assistant, he manages the platform’s core editorial direction, transforming dense government updates and complex banking parameters into structured, clear, and actionable guides for both individual taxpayers and small businesses across North America.
Before launching taxassistant.org, Suresh conducted deep financial and market dynamics research, focusing on asset management, personal wealth optimization, and strategic tax planning. His dedication to data integrity ensures that every piece of news, breakdown, or analysis published under his leadership is rigorously fact-checked by certified tax professionals and aligned perfectly with contemporary regulatory frameworks.